Saving a small amount can feel insignificant when the goal is years or decades away. Compound interest changes the picture because your money has the potential to earn returns, and those returns can generate earnings of their own. Given enough time, growth can accelerate far beyond what your contributions accomplish alone. You don’t need a huge starting balance to benefit, either. Starting early, contributing consistently, and leaving your earnings invested can give even modest savings far more room to grow.
What Compound Interest Actually Means
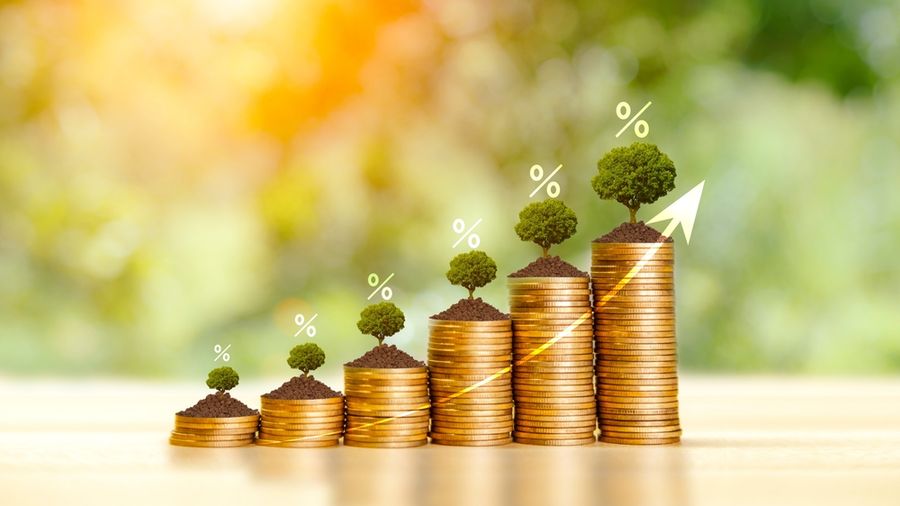
Compound interest is growth calculated not only on the money you originally saved or invested, but also on the earnings that money has already generated. Put simply, your money can start earning money, and then those earnings can potentially produce additional growth. Over time, that repeating cycle can have a powerful effect.
Imagine money earning a return during one period. Instead of withdrawing those earnings, you leave them in the account. During the next period, potential growth applies to a larger balance because the earlier earnings remain included. The process repeats again and again. That’s what separates compounding from simple interest, where earnings are calculated only on the original amount rather than on an expanding balance.
Time Does Much of the Heavy Lifting
One of the greatest benefits of compound growth is that time can matter as much as the amount you contribute. The longer money remains invested or earning interest, the more opportunities previous earnings have to generate additional returns. Growth may look modest in the early years, but the effect can become much more noticeable over longer periods.
That’s why starting with a small amount now can sometimes be more valuable than waiting until you can afford larger contributions. You don’t need to have your finances perfectly organized before beginning. If you have room in your budget, starting earlier gives compounding more time to work. Waiting several years means losing years of potential growth that can’t simply be recreated later.
Small Contributions Can Add Up
Compound growth doesn’t require a large lump sum. Regular contributions can steadily increase the amount available to generate future earnings. Weekly, biweekly, or monthly deposits may seem small on their own, but consistency gives them time to accumulate alongside any growth they earn.
Automatic contributions can make the process easier. You might schedule transfers into a savings account or arrange payroll contributions to a retirement plan. Once the habit is established, saving can happen without requiring a new decision every month. As your income increases, raising your contribution gradually can accelerate progress even further. A long series of modest deposits can eventually create a meaningful balance when paired with enough time and consistent growth.
Reinvesting Earnings Helps Accelerate Growth
Compounding works best when earnings remain in the account rather than being withdrawn. Interest, dividends, or other investment earnings that are reinvested can add to the balance that may generate future returns. Each reinvestment gives your money another opportunity to contribute to future growth.
That principle matters for both savings and investing, although the potential returns and risks are different. Interest-bearing accounts may add earned interest back to the balance automatically. Investment accounts can often reinvest dividends into additional shares. Either way, continually removing earnings interrupts some of the compounding process. Leaving money alone for long-term goals gives previous growth more opportunity to participate in whatever comes next.
The Rate of Return Makes a Difference
Time is important, but the rate your money earns also affects how quickly it can grow. A higher rate can produce significantly different results over long periods because every additional bit of growth may also participate in future compounding.
That doesn’t mean you should chase the highest possible return. Higher potential investment returns generally come with greater risk, and savings intended for short-term needs shouldn't automatically be exposed to market fluctuations. Match where you keep money to the purpose and timeline of the goal. Emergency savings may belong somewhere accessible and relatively stable, while retirement money with decades to grow may allow for a different approach. Compounding is powerful, but good financial planning still requires balancing growth, safety, and access.
Compounding Can Work Against You Too
Compound interest isn't always working in your favor. When you owe money, interest can sometimes be added to an outstanding balance, meaning future interest may be calculated on a larger amount. Credit card debt is a common example of how compounding costs can make balances harder to eliminate.
That’s one reason high-interest debt deserves careful attention. The same mathematical effect that helps long-term savings grow can increase the cost of borrowing when balances remain unpaid. Paying more than the minimum and avoiding unnecessary high-interest debt can help keep compounding on your side of the financial equation. Understanding the concept isn't just useful for saving. It can also help you make smarter decisions about borrowing and repayment.
Consistency Matters More Than Perfect Timing
It can be tempting to wait for the ideal moment to start saving or investing, especially when markets, interest rates, or personal finances feel uncertain. For long-term goals, however, building a consistent habit may matter more than trying to predict exactly when conditions will be best.
Regular contributions also reduce the pressure to make one perfect financial decision. You can start at a comfortable level, increase the amount when your budget improves, and adjust your strategy as your goals change. The important part is giving your money time to work. Compounding rewards patience, and even periods of slower progress can contribute to a much larger long-term result when you keep going.
Give Your Money More Time to Grow
Compound interest shows why seemingly small financial decisions can matter far into the future. Saving a little today may not feel dramatic, but every contribution adds money that has the opportunity to generate its own growth over time.
You don’t need an impressive starting balance to take advantage of compounding. Begin with what your budget comfortably allows, make contributions consistently, and resist the urge to interrupt long-term savings unnecessarily. The combination of time, reinvested earnings, and steady contributions can turn an ordinary savings habit into something much more substantial.